

Midcaps, Two Years On: An Update to Parts I & II
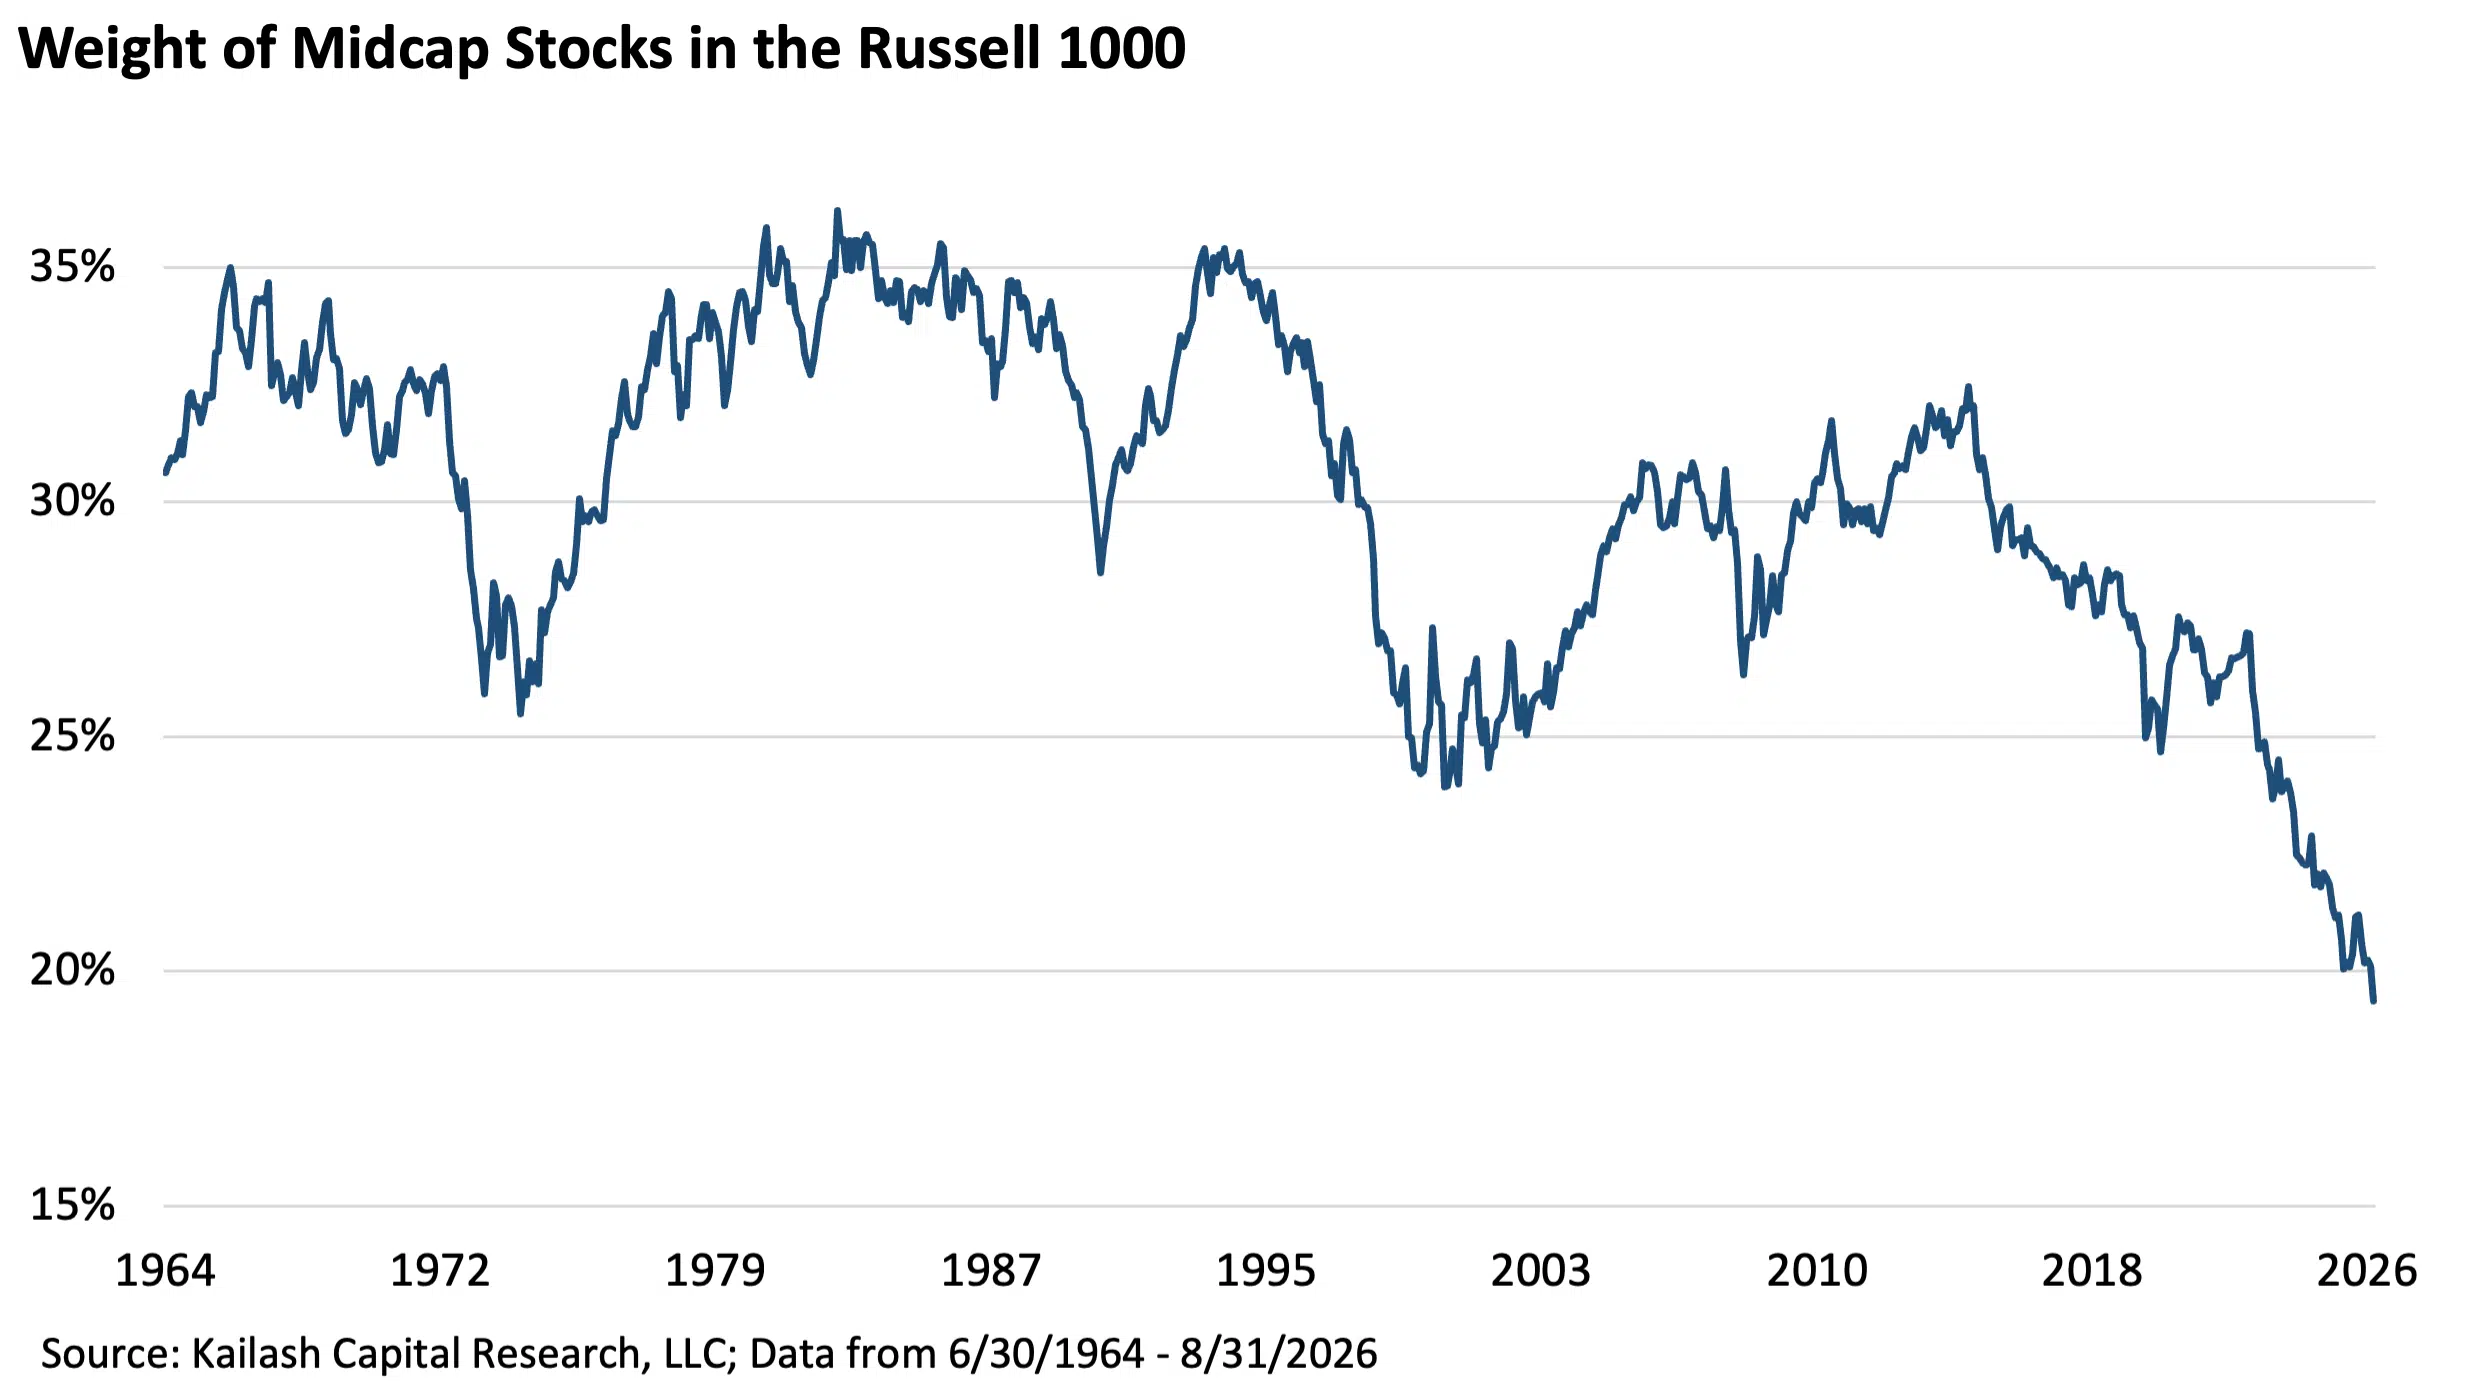
In December 2024 we published Part I and led with a single chart: investors' allocation to midcap stocks had collapsed to a level last seen at the peak of the dot.com bubble. In February 2025 we followed with Part II, which argued that the prices attached to America's largest companies had turned the case for midcaps into one of the fattest pitches we had seen.
Pressure Building: Halliburton Co. (HAL) Is Priced for Shrinking Margins Just as the Pumps Run Tight
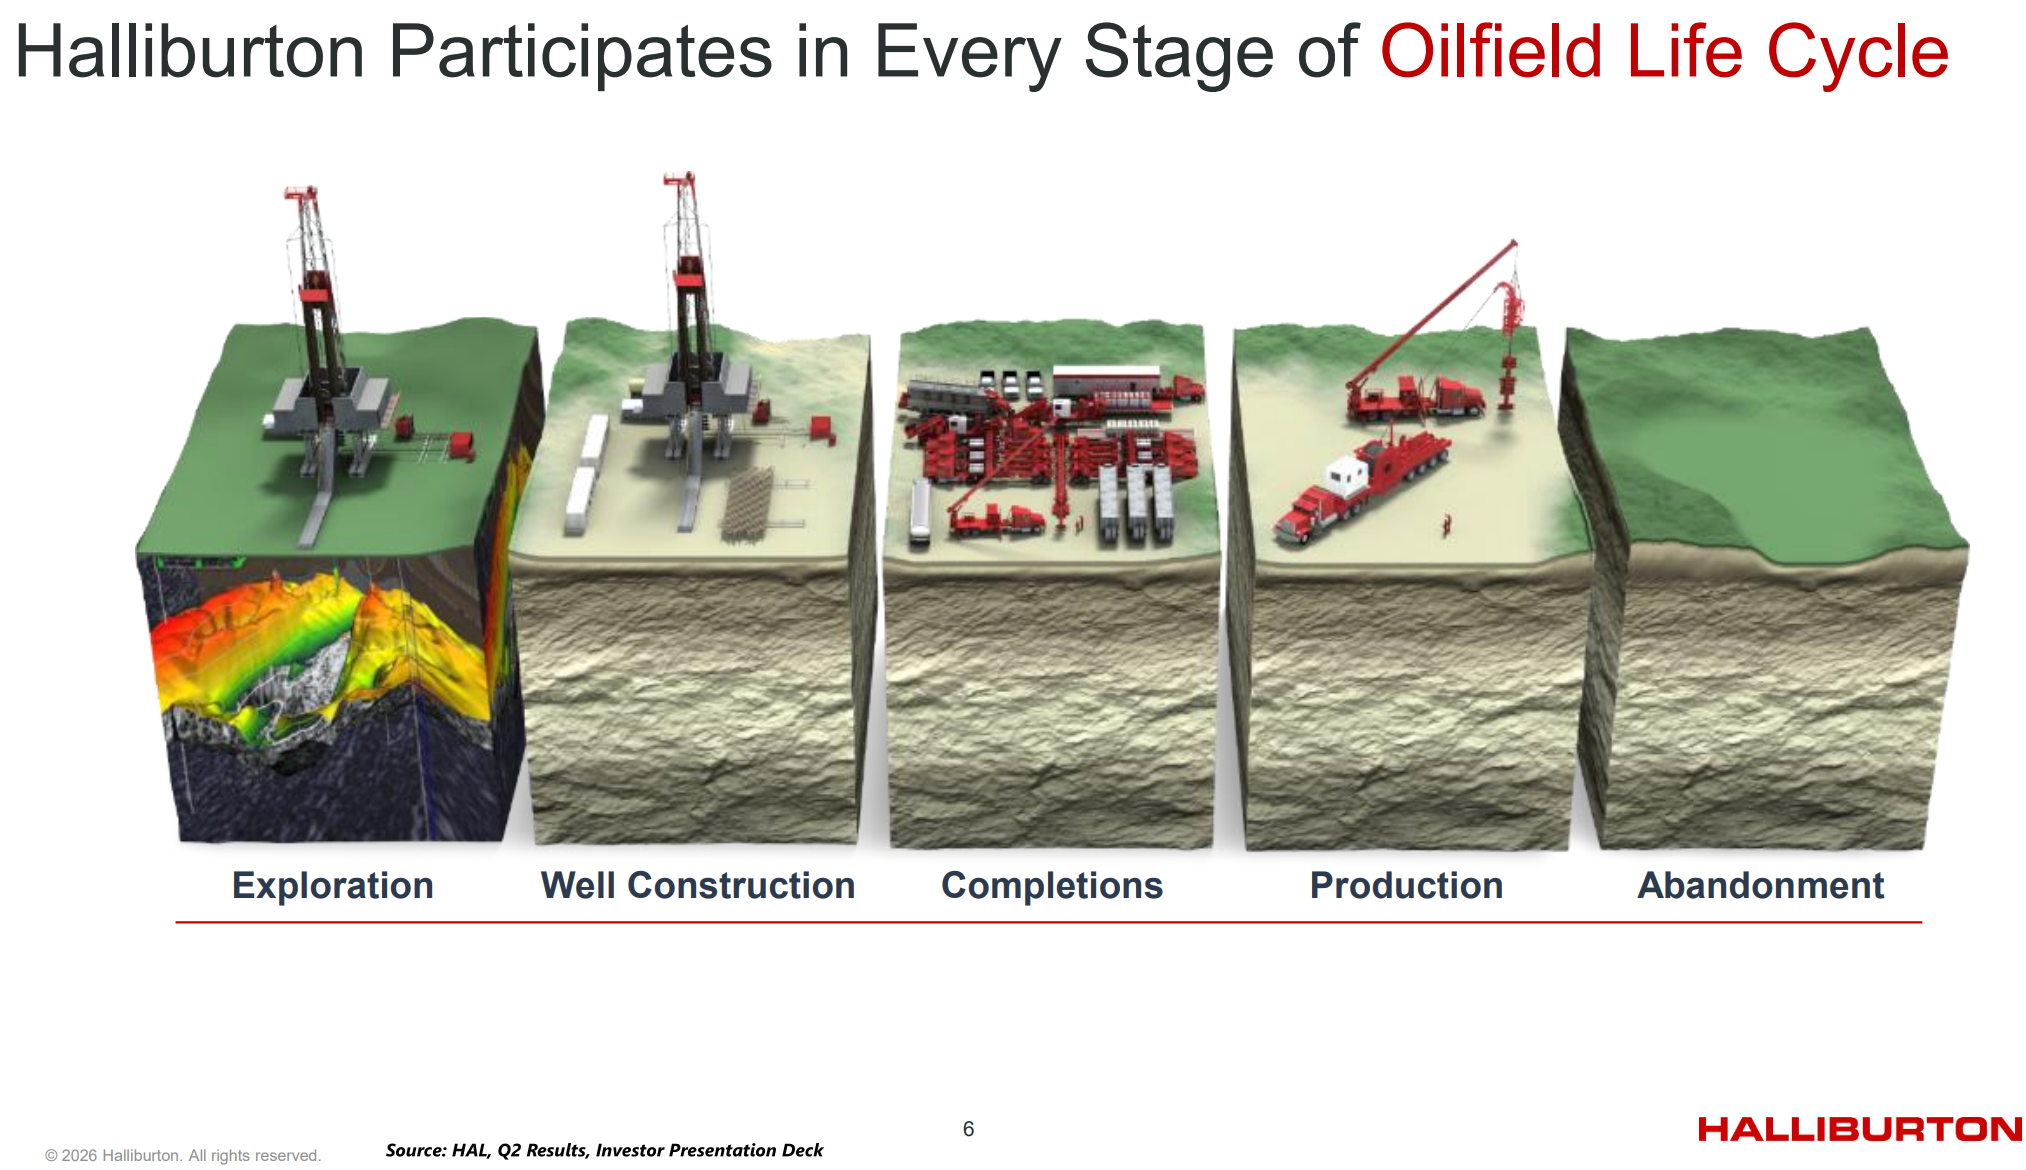
One of the largest oilfield service providers in the world, Halliburton Company (HAL) is widely regarded as the largest hydraulic fracturing, or fracking, and pressure pumping provider in North America.

The High Price of High Volatility
In November 2012, with investors still nursing the wounds of 2008, we published Understanding the Value of Low Volatility and argued that the crowd piling into "low vol" and high-dividend products was paying up for safety at exactly the wrong moment.
The Past, Present, and Future of Nuclear Power
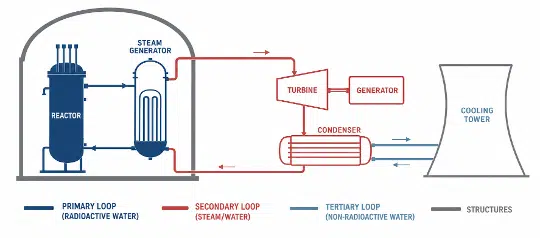
Below we have linked our 16-slide video presentation regarding the past, present, and future of nuclear power. The condensed version of the argument is that after fifty years of stagnation, the industry now has a chance of revival with small modular reactor (“SMR”) technology.
Borrowed Demand — Anything for AI, Part II?
What does a mainframe company’s crash have to do with the AI boom? On July 14th, IBM — a company older than the Federal Reserve — had the worst day in its trading history. The stock fell 25%, erasing roughly $67 billion of market value in a single session and taking out a record that had stood since Black Monday, October 19, 1987.i,ii,iii The S&P 500 barely noticed. Apparently there is nothing to see here — just the largest one-day repricing of a blue chip in nearly four decades.
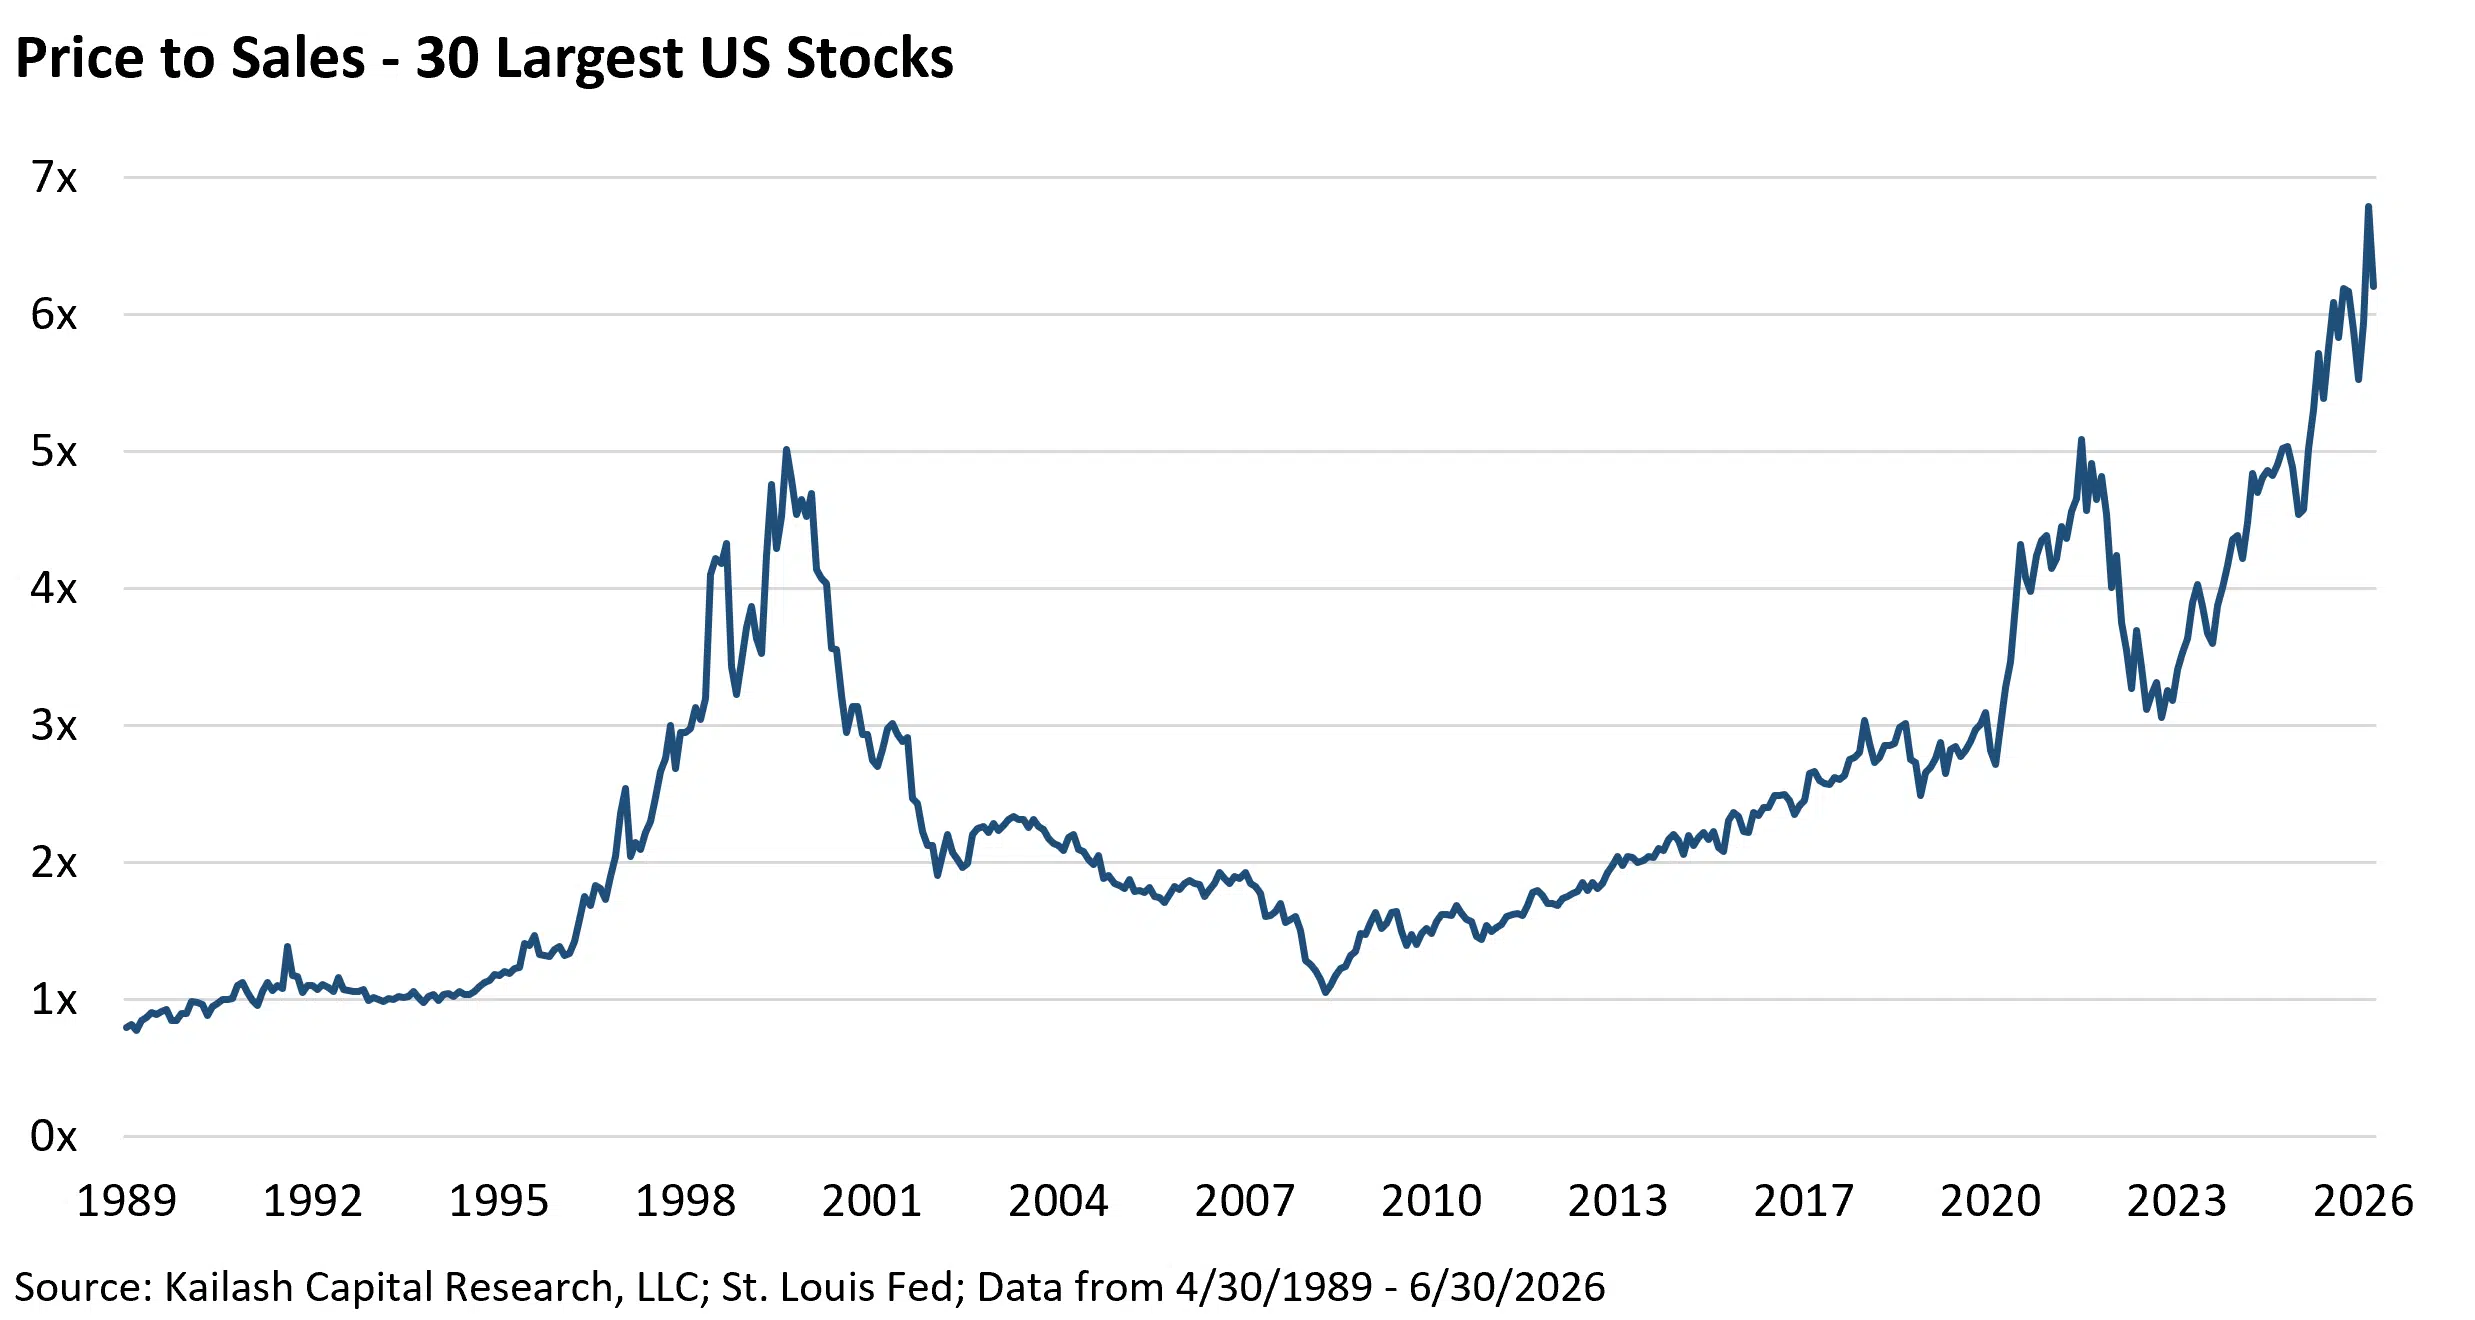
From A Collection of Unkept Promises to the Thirty Largest Stocks
Earlier this month, in The High Price of Promises in SpaceX, we did two things: 1. Walked through the impossible math behind SpaceX’s valuation 2. Documented an almost unbelievable number of broken promises and misleading statements from SpaceX’s CEO on just the most recent Tesla earnings call The most succinct comment in the paper was buried on page two:
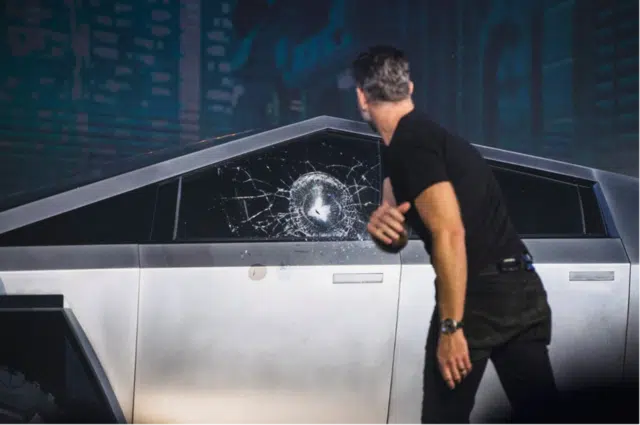
The High Price of Promises in SpaceX
In 2023, KCR noticed that Chamath Palihapitiya was invoking the "Man in the Arena" concept from Theodore Roosevelt's spectacular Citizenship in a Republic speech given at the Sorbonne in 1910. We quickly unleashed our first-ever critique of any one individual in our 15-year history.
Ameriprise Financial, Inc (AMP)
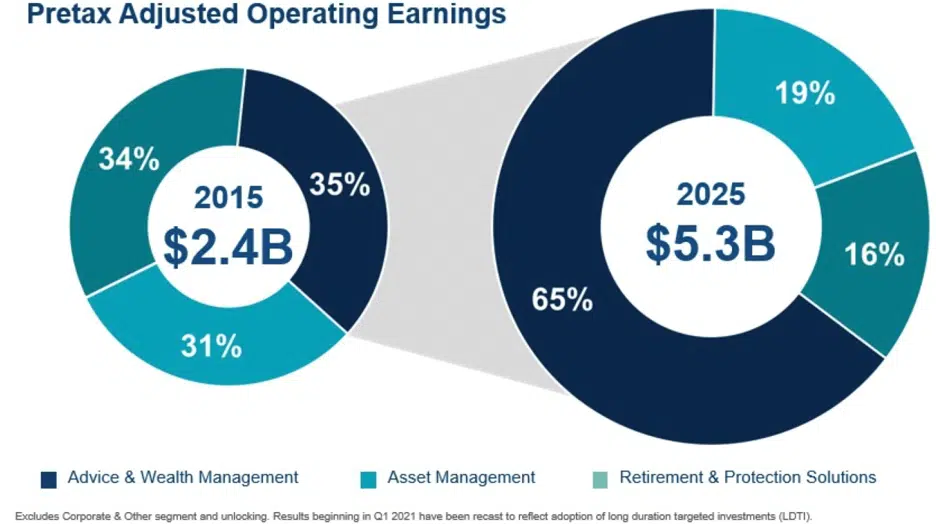
Spun off from American Express in 2005, Ameriprise Financial, Inc. (AMP) is a diversified financial services company. It has three operating divisions: Advice and Wealth Management, by far AMP’s fastest growing unit, makes up about two-thirds of its adjusted operating earnings; while Asset Management and Retirement & Protection Solutions represent 16% and 19%, respectively, of this key financial metric.
The Market and the Economy: Two Sides, Same Coin?
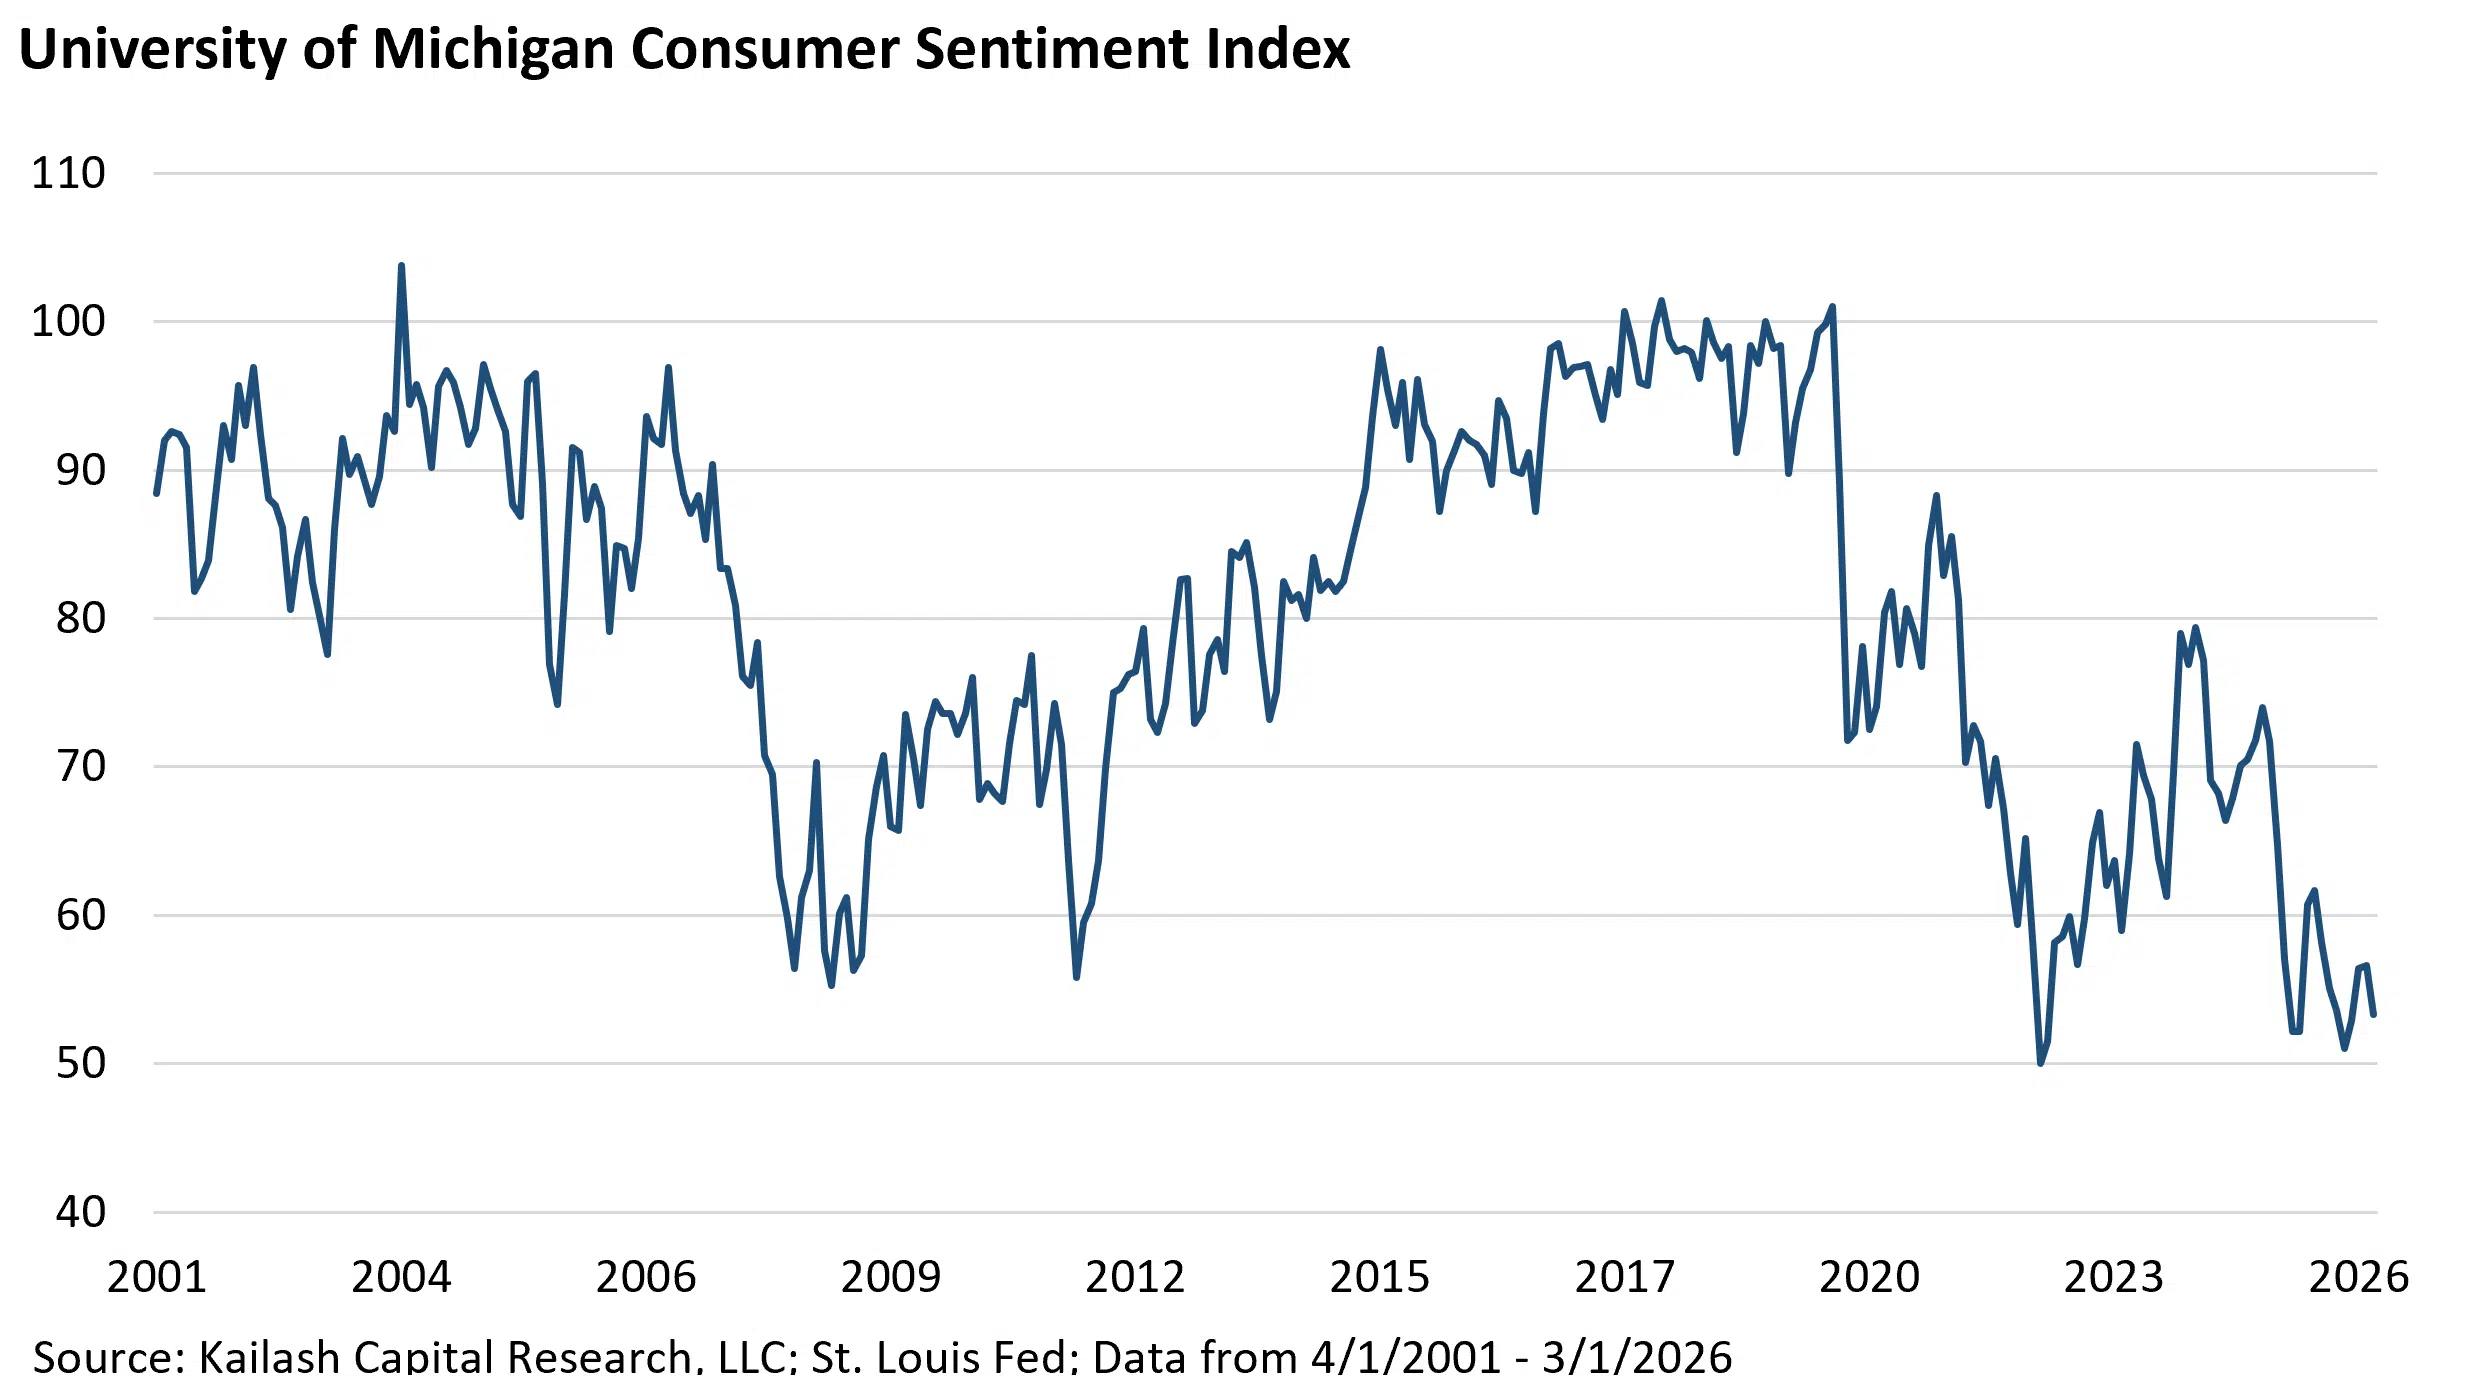
Consumers haven’t been this glum since COVID pandemic supply chain snarls met up with stimulus payments to push inflation up to levels not seen in decades. The University of Michigan Consumer Sentiment Index, which often correlates more tightly with grocery and gas prices than the stock market, is lower than it was during the global financial crisis of 2008.
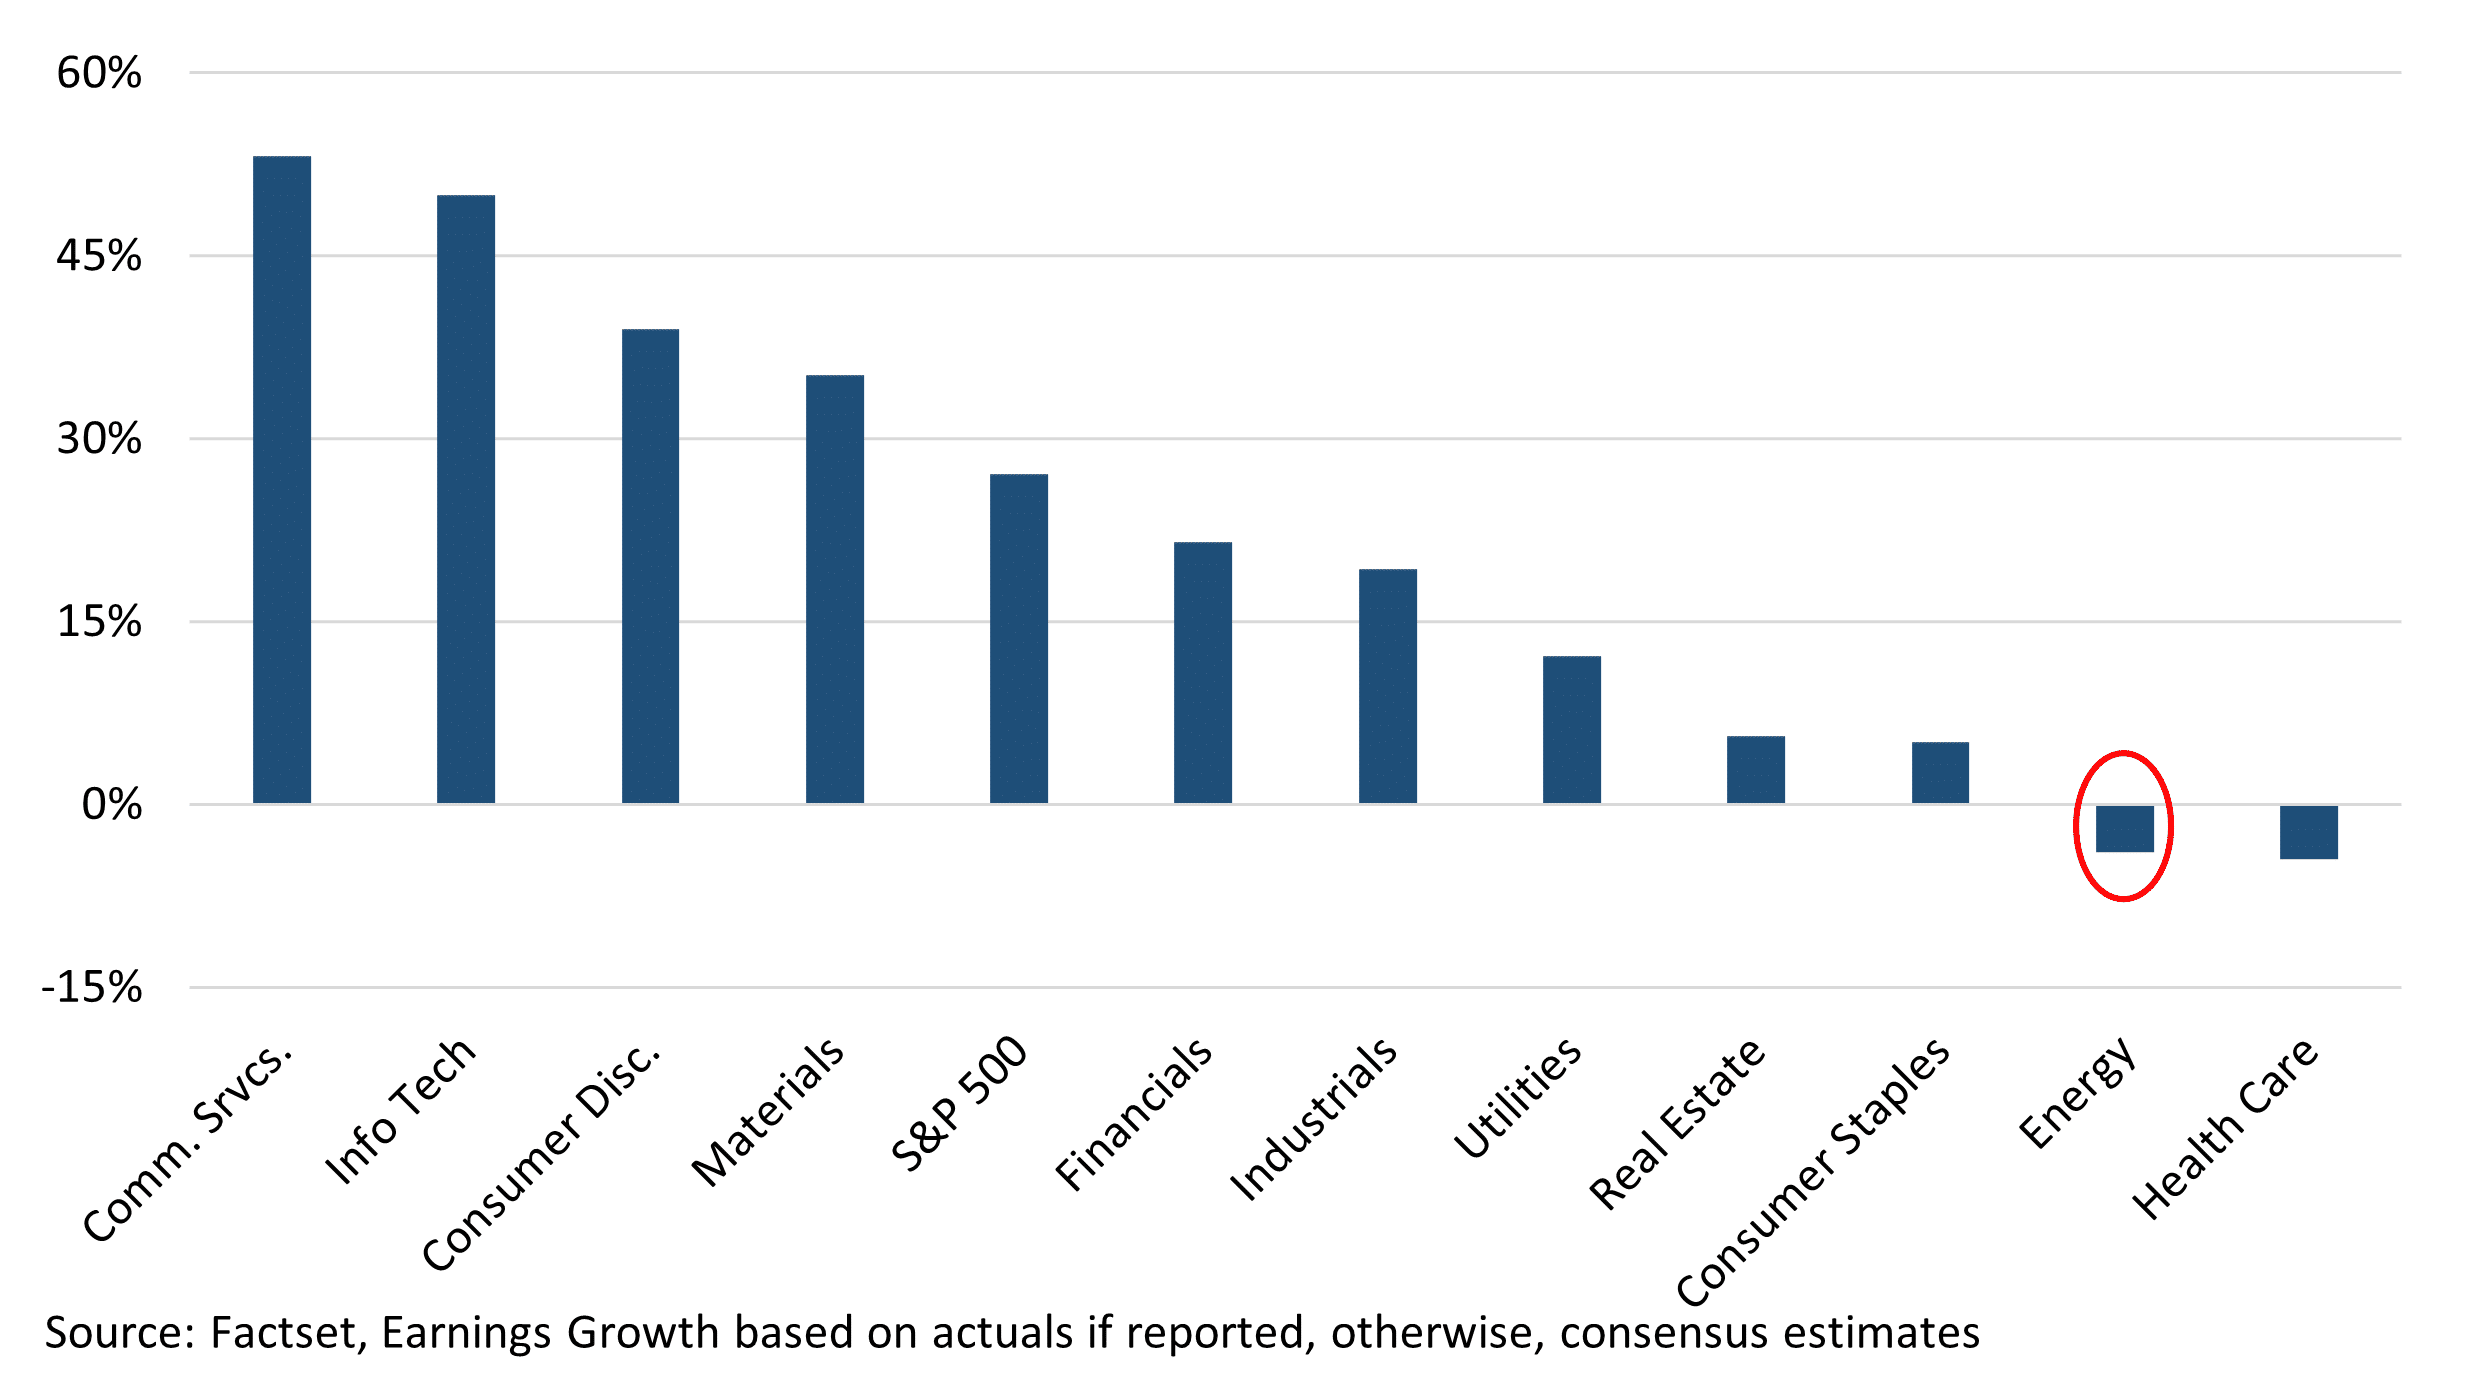
Information Technology & Energy: The Two Tails of Extrapolation Bias
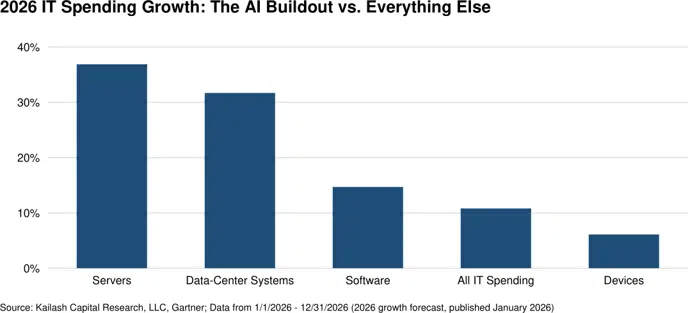
U.S. GDP grew 2% annualized in Q1 2026 after inflation, including gas prices hit their highest since 2022. Private non-residential fixed investment drove 70% of that growth, with "information-processing equipment" alone accounting for one-third of private demand growth over the past 12 months.
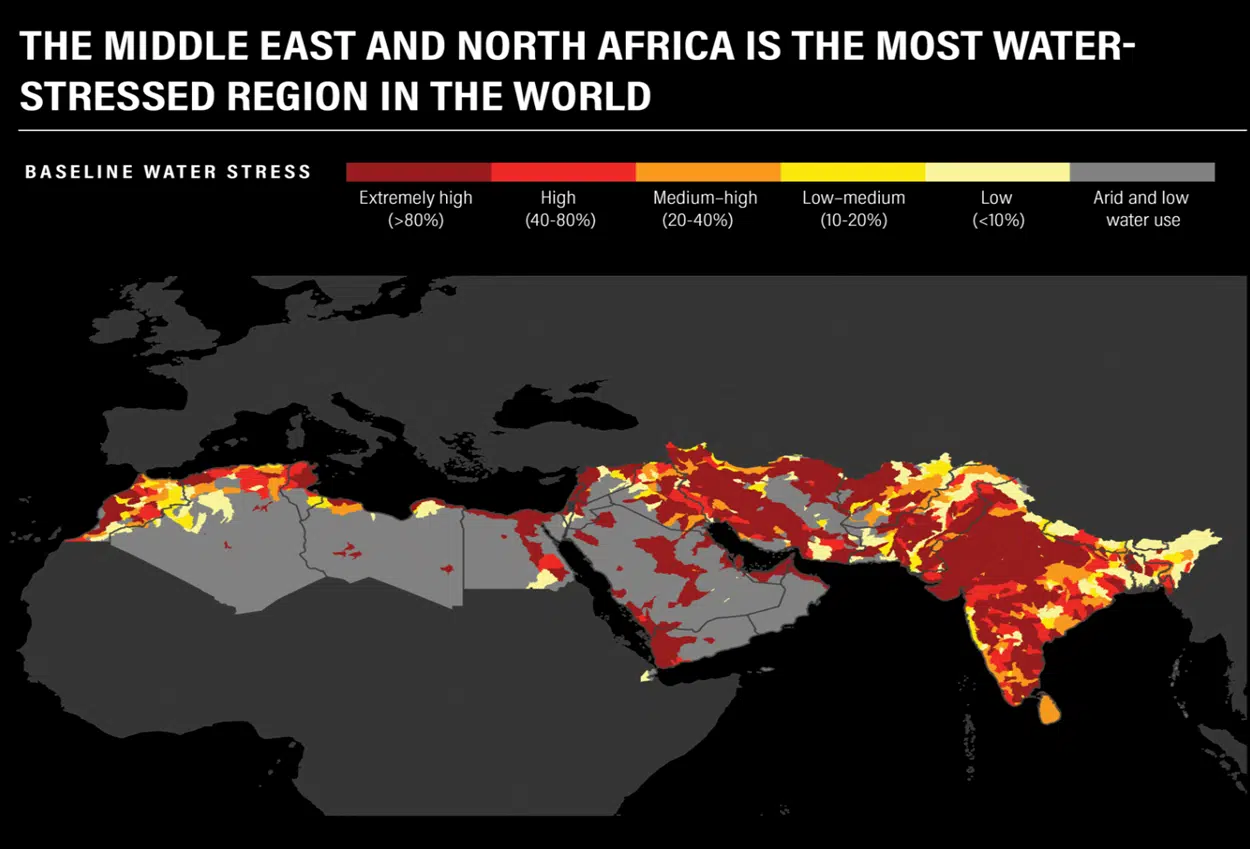
Water, Food, & Fuel: Is the Market Mispricing the War on Iran?
Water Risk from a Prolonged War with Iran Markets have rightly fixated on what the Iran war means for oil and gas flows through the Strait of Hormuz—but in doing so, they have largely ignored a vulnerability that may prove even more destabilizing: the Middle East's near-total dependence on desalinated water.
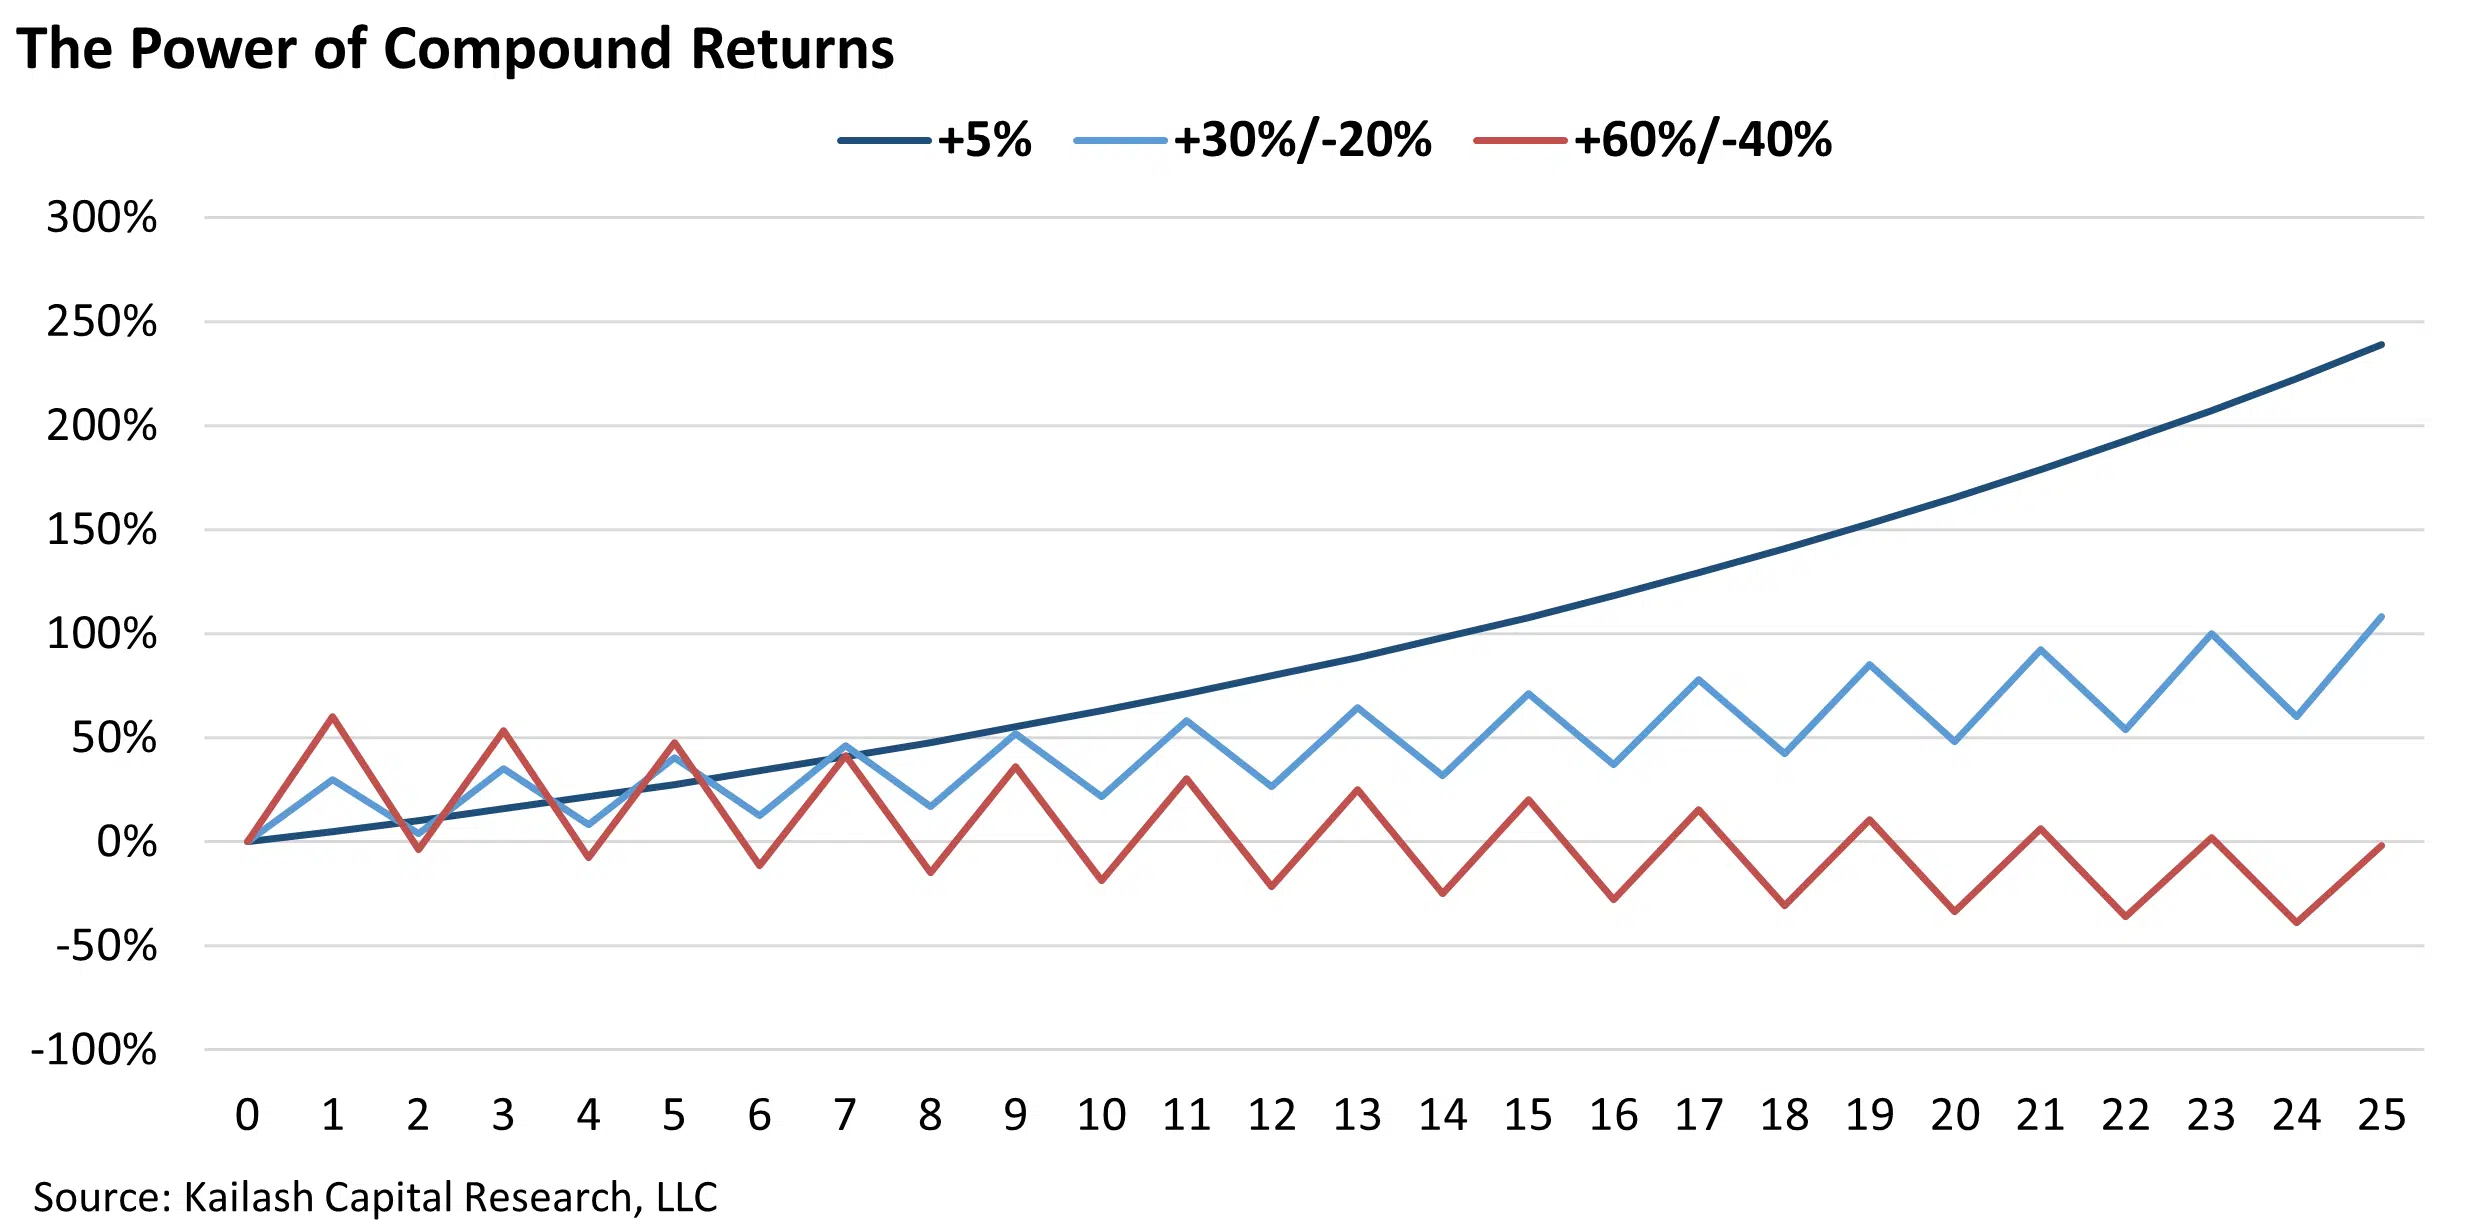
Should Retail Investors Head to the Casino?
Leveraged ETFs look like a shortcut: twice (or three times) the action of a stock, in a tidy wrapper you can buy in a brokerage account. The problem—explained plainly in this paper—is that the shortcut is built on a misunderstanding.